
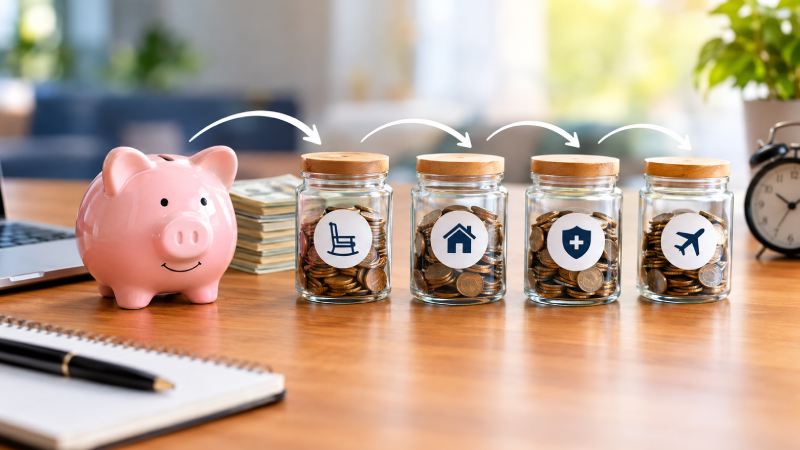
The pay yourself first budget, or reverse budgeting, is a cash management strategy where you automatically route a set portion of income into savings and retirement accounts on payday before allocating money toward living expenses or discretionary spending.
Rather than saving whatever remains at month’s end, this system flips traditional personal finance priorities by treating future wealth goals as non-negotiable monthly obligations.
By automating account deposits immediately upon receiving a paycheck, individual spending naturally compresses to fit the remaining checking balance without tedious transaction tracking.
This proven methodology secures long-term capital expansion effortlessly while completely eliminating daily budget fatigue.
How Does Reverse Budgeting Compare to Traditional Methods?
Comparing classic expense tracking against top-down saving reveals fundamental differences in daily execution, behavioral psychology, and ongoing administrative effort for managing household cash flow.
Effort Requirements and Execution Friction
Traditional expense tracking requires logging every transaction, causing administrative burnout and budget abandonment over time. Reverse budgeting flips this friction point by focusing strictly on upfront automation setup.
Once automatic transfers are established, ongoing daily maintenance is virtually non-existent, making wealth accumulation effortless, consistent, and sustainable without micromanaging daily coffee purchases or logging receipts.
Weaponizing Behavioral Psychology
Classic budget plans struggle against Parkinson’s Law, where spending naturally expands to fill whatever cash balance remains in checking accounts. Paying yourself first weaponizes this exact behavioral rule by moving savings out of sight immediately.
Compelling your checking balance into a smaller pool forces discretionary spending to adjust naturally without relying on willpower or tracking individual output categories.
Ideal Candidate Profiles for Success
Standard line-item tracking works best for individuals facing severe overspending or navigating complex debt paydowns.
In contrast, top-down automated frameworks serve income-stable individuals who wish to accumulate wealth without tracking daily receipts.
Matching your personal balance sheet to the correct methodology prevents unnecessary friction and ensures consistent progress toward long-term goals.
How Do You Set Up a Pay Yourself First Budget?
Executing an automated savings plan requires a structured order of operations to build long-term wealth safely while maintaining sufficient liquidity for mandatory monthly living expenses.
Establishing Your Income Baseline and Target
Begin by calculating your exact net take-home salary from your primary paycheck. Financial planners recommend setting an initial savings target between 10% and 20% of net income.
On a $5,000 monthly take-home salary, a standard 20% savings rate directs $1,000 straight into wealth accounts before addressing mandatory living expenses or discretionary spending.
Routing Capital Into Dedicated Accounts
Divide your upfront savings target across distinct financial buckets aligned with your timeframe.
For example, a $1,000 monthly target can be allocated into workplace retirement or Roth IRA accounts ($400), high-yield emergency reserves ($300), and mid-term targets like a house or car ($300).
The remaining $4,000 balance covers fixed bills and guilt-free personal spending.
Configuring Pre-Checking and Post-Checking Automation
Establish payroll deductions for employer 401(k) or pension plans so capital moves before touching checking accounts.
Next, log into your banking portal (such as Ally Bank or Marcus by Goldman Sachs) to schedule automatic post-paycheck transfers for cash savings exactly one day after payday. This sequence prevents accidental account overdrafts while securing consistent growth.
Monthly Income Allocation Framework
Reviewing real-world monthly income distributions demonstrates how automated contributions balance immediate living requirements, long-term investments, and flexible lifestyle expenditures across distinct paycheck tiers.
| Take-Home Income Tier | Savings Rate Target | Wealth Bucket Allocation | Mandatory Bills Allocation | Discretionary Balance |
|---|---|---|---|---|
| $4,000 Take-Home | 20% ($800) | $800 (High-Yield Savings & Roth IRA) | $2,000 (Rent, Utilities, Insurance, Debt) | $1,200 (Groceries, Dining, Fun) |
| $5,000 Take-Home | 20% ($1,000) | $1,000 ($400 Retirement, $300 Emergency, $300 Goals) | $4,000 Remaining Balance Cap (80%) | Fixed Bills & Discretionary Cash |
| $6,000 Take-Home | 15% ($900) | $900 (Retirement & Emergency Reserves) | $3,100 (Fixed Obligations & Essentials) | $2,000 (Flexible Discretionary Cash) |
Key Execution Rules for Cash Flow Management
- Prioritize Retirement Tax Shields: Automate workplace 401(k) or IRA transfers via direct deposit so taxable gross income decreases automatically.
- Lock In Emergency Liquidity: Direct automated cash flows into high-yield savings accounts until three to six months of living expenses are secured.
- Cap Mandatory Obligations: Ensure fixed monthly commitments like housing, utilities, insurance, and minimum debt payments do not exceed 80% of total take-home pay.
- Isolate Discretionary Balances: Use remaining checking funds guilt-free for groceries, dining out, entertainment, and personal hobbies without transaction tracking.
What Are the Disadvantages of Reverse Budgeting?
While top-down automation accelerates wealth building, implementing this system blindly creates hidden financial hazards that can compromise short-term cash flow and overall net worth.
The Toxic High-Interest Debt Exception
Automating savings deposits while maintaining high-interest credit card debt between 15% and 30%+ APR is mathematically flawed. Generating a 4% yield in savings while paying 24% on card balances destroys net worth rapidly.
Under this framework, high-interest debt payoff must become your primary automated savings target to guarantee a return equal to the interest avoided.
Bank Overdraft Triggers and Timing Risks
Automated transfer mechanics rely on precise timing relative to your primary deposit cycle. If recurring savings withdrawals execute before delayed payroll deposits clear or large utility bills hit, your account risks costly overdraft fees.
Scheduling automated transfers at least twenty-four hours after expected paycheck deposits creates an essential liquidity buffer.
The Sinking Fund and Irregular Expense Blindspot
Draining remaining checking balances on lifestyle spending leaves households vulnerable to non-monthly commitments like annual vehicle registrations, insurance premiums, or holiday gifts.
Unplanned irregular bills force individuals to raid emergency funds repeatedly. Maintaining dedicated sinking fund buffers prevents unexpected expense disruptions and protects cash reserves.
Income Floor Limitations for Variable Earners
Fixed automated transfer amounts require predictable income cycles to operate safely. Freelancers, gig economy workers, or commission-based sales professionals face cash starvation during low-income months if fixed automated transfers trigger.
Variable earners must calculate conservative baseline floors or adjust transfer rules dynamically to avoid starving checking accounts of basic rent money.
10-Year Compounding Wealth Growth Simulation
Consistently directing capital into low-cost market index funds harnesses passive compounding, turning routine monthly transfers into substantial long-term wealth over multi-year investment horizons.
| Investment Horizon | Cumulative Principal Invested | Total Value at 7% Return | Passive Compounding Gain |
|---|---|---|---|
| Year 1 | $12,000 | $12,467 | $467 |
| Year 3 | $36,000 | $40,058 | $4,058 |
| Year 5 | $60,000 | $71,593 | $11,593 |
| Year 7 | $84,000 | $110,181 | $26,181 |
| Year 10 | $120,000 | $174,094 | $54,094 |
Takeaways From Compounding Models
- Non-Negotiable Discipline: Treating monthly contributions ($1,000) as mandatory bills guarantees consistent capital deployment regardless of short-term market fluctuations.
- Accelerated Passive Returns: Over a ten-year timeline, compounding interest generates over $54,000 in purely passive market growth beyond principal contributions.
- Broad Market Exposure: Routing automated contributions into low-cost index funds provides diversified market growth without active stock picking.
Is the Pay Yourself First Strategy Right for You?
Evaluating your personal balance sheet, debt obligations, income consistency, and spending habits helps determine whether top-down automated saving aligns with your immediate financial profile.
When to Choose Reverse Budgeting
This framework works best for stable salary earners receiving predictable payroll deposits who want guaranteed investment growth without logging daily receipts.
It suits individuals with established emergency cash buffers and zero toxic high-interest credit card debt. If you desire a stress-free wealth-building routine that operates on autopilot, reverse budgeting provides an ideal solution.
When to Avoid or Modify the System
Avoid fixed automated transfers if you carry high-interest credit card debt, experience wildly fluctuating freelance income, or frequently drain checking balances days before payday.
Impulsive spenders who struggle with unmonitored purchases also require strict category limits. Under these conditions, prioritize debt payoff, establish a stable cash cushion, or adopt line-item category tracking first.
Frequently Asked Questions About Reverse Budgeting
Is paying yourself first considered a formal budget?
Yes, it is a recognized top-down budgeting framework that focuses on securing savings inputs first rather than tracking individual output expenses. Once automated targets are funded, the remaining balance serves as a single spending pool.
How much should a beginner pay themselves first?
Financial planners widely recommend aiming for a baseline savings rate between 10% and 20% of net take-home pay. Beginners can start at 5% or 10% and increase automated transfers gradually as cash flow stabilizes.
What happens if automated transfers trigger during low balance periods?
If automated transfers execute before deposits land or large bills clear, bank accounts can incur costly overdraft fees. To prevent this, schedule automatic transfers one to two business days after payday and maintain a checking buffer.
Where should automated savings funds be deposited?
Funds are typically split across workplace 401(k) or Roth IRA accounts for retirement, high-yield savings accounts for emergency reserves, and separate accounts for mid-term financial targets.
Start Automating Your Financial Future
By automating your savings target on payday, you eliminate manual transaction tracking and guarantee continuous wealth expansion.
Begin by establishing a realistic 10% to 20% target, configuring automatic transfers one day post-payday, and enjoying guilt-free spending on your remaining balance. Review your account setup today to build a stress-free financial foundation.





