
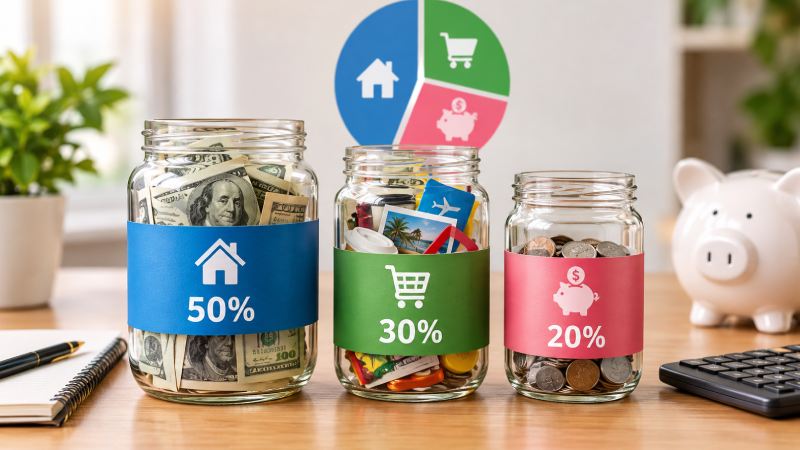
The 50/30/20 rule of budgeting is a percentage-based personal finance framework that divides monthly net (after-tax) income into three core spending categories: 50% for essential needs, 30% for discretionary wants, and 20% for future savings and debt repayment.
Formulated by Elizabeth Warren and Amelia Warren Tyagi in 2006, this framework replaces detailed line-item expense tracking with macro-allocations.
It provides structural guardrails to ensure essential obligations remain covered while securing ongoing wealth accumulation and lifestyle flexibility. Automating these three spending buckets on payday eliminates decision fatigue and builds long-term monetary discipline.
How Does the 50/30/20 Budgeting Rule Work?
Understanding how the 50/30/20 budget framework divides net income into three distinct buckets establishes the structural baseline necessary for automating monthly cash flow and controlling household expenses.
Allocating 50 Percent for Essential Survival Needs
Fifty percent of net take-home pay covers non-negotiable living obligations essential for survival and employment.
Essential obligations encompass housing costs like mortgage or rent, property taxes, home insurance, basic utilities, groceries, transportation expenses, healthcare premiums, and required minimum loan payments.
Keeping fixed obligations within this half-income threshold protects households against financial shocks and default risks.
Allocating 30 Percent for Discretionary Lifestyle Wants
Thirty percent of after-tax earnings supports discretionary lifestyle upgrades that enhance personal quality of life.
Discretionary categories include restaurant dining, coffee shop visits, streaming subscriptions, entertainment events, vacation travel, non-essential apparel, and recreational hobbies.
These discretionary expenses can be completely eliminated or reduced during unexpected cash flow emergencies without damaging core household stability.
Allocating 20 Percent for Future Savings and Debt Payoff
The final twenty percent builds long-term wealth and permanent asset security.
Capital in this bucket builds liquid emergency reserves covering 3 to 6 months of expenses in high-yield savings accounts, funds individual retirement accounts or brokerage contributions, and pays down extra debt principal.
Prioritizing this category guarantees steady net worth expansion over time.
Monthly Income Allocations and Dollar Breakdown Benchmarks
Converting percentage targets into concrete monthly dollar amounts illustrates how the 50/30/20 system applies across different salary levels, offering clear benchmarks for real-world execution.
| Net Monthly Income | 50% Needs Limit | 30% Wants Limit | 20% Savings Limit | Primary Operational Focus |
|---|---|---|---|---|
| $3,000 | $1,500 | $900 | $600 | Establishing emergency cash reserves and capping fixed rent. |
| $4,000 | $2,000 | $1,200 | $800 | Standard distribution balancing bills, lifestyle, and wealth building. |
| $5,000 | $2,500 | $1,500 | $1,000 | Accelerated debt reduction or expanding investment accounts. |
| $8,000 | $4,000 | $2,400 | $1,600 | Preventing lifestyle inflation while maximizing retirement deposits. |
| $10,000 | $5,000 | $3,000 | $2,000 | Inverting allocations toward aggressive early retirement targets. |
Applying these specific figures clarifies monthly spending boundaries. For instance, a worker taking home $4,000 monthly routes $2,000 to fixed survival costs, $1,200 to personal pursuits, and $800 directly into automated wealth vehicles on payday. This systematic allocation prevents overallocation to non-essentials.
Why Is the 50/30/20 Rule So Effective?
Adopting a macro-level financial strategy offers psychological and structural advantages over traditional line-item budgets, fostering consistent adherence without inducing mental burnout or decision fatigue.
Elimination of Budgeting Fatigue and Tracking Stress
Traditional budgets fail because categorizing dozens of daily micro-transactions causes cognitive exhaustion. The 50/30/20 rule focuses exclusively on three macro-allocations, eliminating tedious line-item tracking.
Managing three broad categories reduces financial stress while maintaining clear spending boundaries.
Guilt-Free Discretionary Spending Within Set Limits
Reserving a dedicated 30% portion for personal enjoyment removes emotional guilt from discretionary purchases.
Because essential survival costs and future investment goals are fully funded first, spending within the designated wants category requires no self-reproach, preserving personal fulfillment alongside disciplined money management.
Automatic Implementation of Paying Yourself First
Setting aside 20% for wealth building on payday reverses the common failure of saving only leftover money at month-end.
Paying yourself first enforces automatic capital accumulation, guaranteeing that long-term investment accounts and emergency cash reserves grow consistently regardless of discretionary spending temptation.
Built-in Protection Against Lifestyle Creep
As career advancement yields higher earnings, fixed spending caps adjust proportionally. Scaling spending caps automatically prevents fixed living costs from expanding unchecked.
This proportional growth maintains structural financial stability and ensures that income increases directly boost overall wealth reserves.
Core Limitations and Structural Drawbacks
While highly effective for average incomes in moderate-cost areas, strict percentage rules face mathematical limitations when applied to extreme economic realities or heavy debt burdens.
The High Cost of Living Housing Bottleneck
Metropolitan regions with elevated real estate prices often force housing and utility costs beyond 50% of starting salaries. When basic shelter consumes 60% or 70% of net pay, strict adherence to standard percentage targets becomes mathematically impossible.
Forcing standard allocations under extreme housing costs creates severe financial deficits.
The Wealth Drag of Compounding High-Interest Liabilities
Allocating only 20% toward total savings and debt payoff proves inefficient when carrying high-interest credit card balances above 20% APR.
Compounding interest charges bleed accumulated net worth faster than modest savings generate returns. In high-interest debt situations, discretionary spending must be drastically reduced to eliminate expensive debt principal.
Challenges Faced by Lower-Income Households
Workers earning lower absolute incomes frequently allocate over 50% of take-home pay strictly to basic survival necessities.
When groceries, rent, and healthcare consume the vast majority of earnings, restricting essential spending to half income is unachievable without earning growth or structural subsidies.
Lifestyle Inflation Risks for Upper-Income Earners
High earners taking home substantial monthly salaries risk accelerating lifestyle inflation if they spend a full 30% on discretionary items.
Furthermore, capping savings at 20% may unnecessarily delay early retirement goals for high earners who possess the capacity to invest significantly larger capital proportions.
How Can You Adjust the 50/30/20 Rule for Your Situation?
Customizing the baseline percentages allows individuals to adapt the framework to unique geographical costs, aggressive debt reduction goals, or early retirement ambitions.
- High Cost of Living Adjustment (60/20/20 Split): Temporarily expand the essential needs bucket to 60% while reducing discretionary spending to 20% to accommodate high urban rent obligations.
- Hyper-Expensive Metropolitan Split (70/15/15 Shift): Shift essential obligations to 70%, cap discretionary wants at 15%, and maintain a baseline 15% allocation for emergency savings.
- Aggressive Debt Payoff Model: Reduce discretionary lifestyle spending to 10% or less, redirecting all surplus cash flow to extinguish high-interest credit card principal.
- High-Earner Wealth Acceleration Inversion (30/20/50 Split): Cap essential living costs at 30%, restrict discretionary wants to 20%, and direct 50% of take-home pay toward investment vehicles and early independence goals.
- Allowance Framework for Kids: Adapt allocations for young learners using allowance or cash gifts divided into 50% Savings, 30% Spending (Wants), and 20% Giving or Sharing.
Step-by-Step Implementation and Automation Guide
Executing a successful transition to proportional budgeting requires a structured three-phase plan that audits current cash flow, automates bank transfers, and monitors monthly spending drift.
Phase One Audit of Net Monthly Take-Home Pay
Begin implementation by reviewing official paystubs to identify exact net take-home earnings. Calculate total income after federal, state, and local payroll taxes are deducted.
Exclude automatic pre-tax retirement deductions like 401(k) contributions from this net figure, or count them as an added bonus toward overall financial targets.
Phase Two Automated Bank Account Structuring
Establish separate bank accounts and program automatic transfers to execute instantly on payday.
Direct 20% of net earnings into a high-yield savings or brokerage account, and route 50% into a primary checking account dedicated exclusively to automated bill payments. Leave the remaining 30% for discretionary card spending.
Phase Three Monthly Discretionary Drift Review
Perform a quick review every 30 days to evaluate total discretionary spending. If discretionary purchases exceed the 30% limit, analyze recent transactions to spot subscription overlaps or excessive dining expenses.
Adjust checking account permissions and spending limits for the upcoming month to maintain precise category alignment.
Frequently Asked Questions
Which Expense Category Covers Minimum Credit Card Payments?
Minimum required credit card or loan payments belong strictly in the 50% Needs category. These legal minimums represent non-negotiable obligations necessary to avoid default and credit score damage.
However, any extra payments made above the minimum requirement to accelerate debt elimination belong in the 20% Savings and Extra Debt bucket.
How Should Pre-Tax 401k Retirement Contributions Be Handled?
If your employer deducts retirement contributions directly from your gross salary before depositing your paycheck, treat those funds as an added bonus or adjust your net income calculations accordingly.
You can calculate percentages based strictly on deposited net pay or add pre-tax contributions back into total net income to reflect true savings progress.
Can the Percentages Be Adjusted During Financial Emergencies?
Yes, percentage targets should be treated as flexible guardrails rather than immutable laws.
During sudden income losses, medical emergencies, or periods of severe inflation, discretionary spending should be slashed immediately to preserve essential survival needs and maintain baseline savings buffers. Realign target allocations as financial stability returns.
Conclusion: Building Sustainable Financial Growth
The 50/30/20 budgeting rule serves as an exceptional baseline that eliminates tracking complexity while establishing consistent savings habits.
By categorizing income into essential needs, discretionary wants, and future savings, individuals build a resilient framework that adapts as career earnings grow.
While high living costs or heavy debt burdens may require temporary structural adjustments, maintaining proportional awareness remains a proven path to lasting monetary independence.
Start by auditing your net take-home pay today, automating your bank transfers on payday, and refining your allocations over time to achieve complete balance.





